Correlation Isn’t Enough: How to Test Whether “A Moved B” in Markets
Published on September 19, 2026
Why Time-Series Relationships Are Easy to Misread
Markets constantly generate explanations. Yields rise and stocks fall, so higher yields are blamed. The dollar strengthens and another asset moves at the same time, so the currency move becomes the explanation.
These stories can be plausible. The problem is that several different stories can often explain the same market move.
Correlation alone does not resolve that problem. Two series can move together because one leads the other, because both respond to a third factor, or because the relationship happened to be strong during a particular market regime. A chart may make the connection look obvious even when the timing, direction, and stability of that relationship remain unclear.
With time-series data, when something moved matters almost as much as whether the two series moved together.
That is the problem CauseDecode is being designed to examine.
What CauseDecode Is Trying to See
CauseDecode starts with a simple market question: Does this factor really matter?
The main unit of analysis is one hypothesis involving primarily two series. Rather than asking an AI to generate another explanation for a market move, the goal is to take an existing hypothesis and test it from several angles.
For example, if Series A and Series B appear related, we want to know more than whether their contemporaneous correlation is high. We also want to examine whether one tends to move before the other, how that relationship changes across lags, whether past values contain additional predictive information where the method is applicable, and whether the relationship remains stable over time.
The goal is not to reduce all of that evidence to a black-box answer such as “causal” or “not causal.”
Observed time-series data rarely justify that kind of conclusion on their own. CauseDecode is instead designed to show the underlying evidence first and help users judge whether a market hypothesis holds up under closer examination.
Start by Defining the Analysis Series
Before comparing two time series, we first need to decide what is actually being compared.
The same raw market series can mean very different things depending on how it is transformed. A price level is not the same object as a daily return. A yield level is different from a daily change. Comparing two series without making those choices explicit can produce results that look meaningful but answer a different question from the one we intended to ask.
In CauseDecode, this preparation is handled as part of the analysis workflow rather than treated as an afterthought.
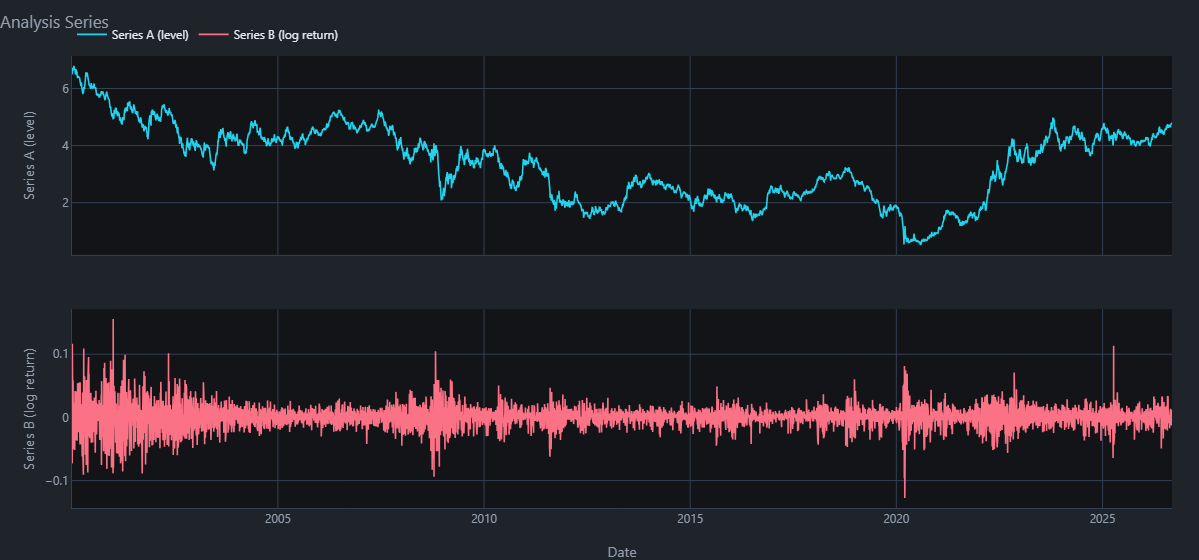
The point is not that one transformation is always correct. The point is that the transformation must match the question being tested.
Once the analysis series are defined and aligned, we can begin looking at the timing of the relationship.
Use Lead-Lag (CCF) to Examine What Moves First
A standard correlation compares two series at the same point in time. But in markets, the more interesting question is often whether one series tends to move before the other.
Lead-Lag analysis addresses that question by shifting the two series relative to each other and recalculating their relationship across different lags.
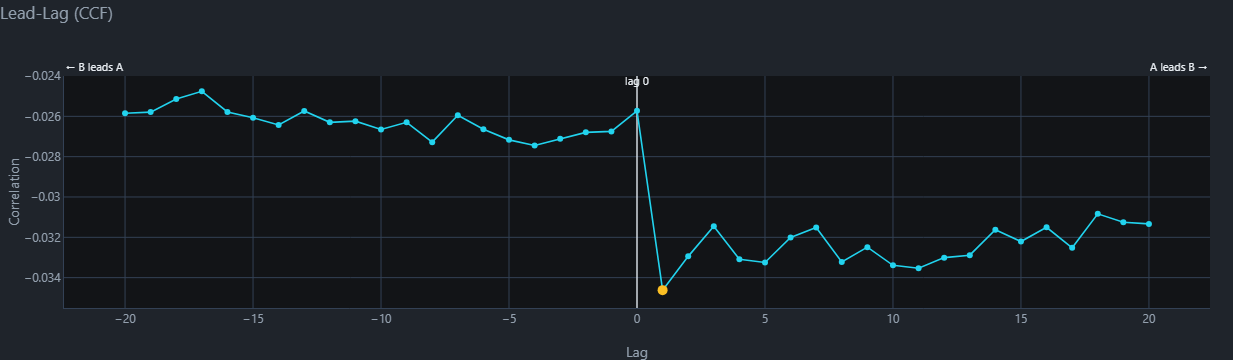
In the chart, the two sides of lag 0 represent opposite timing directions. This makes it possible to inspect whether the relationship is concentrated around the same day or whether a stronger pattern appears when one series is shifted forward or backward.
The important point is to look at the profile, not just the single strongest point.
A large correlation at one lag may be interesting, but it does not automatically establish a meaningful lead-lag relationship. Neighboring lags, the overall shape of the profile, statistical uncertainty, and other evidence all matter.
And even when one side of the profile appears stronger, that still does not mean that Series A has been proven to cause Series B.
Correlation Can Be Visible and Still Be Insufficient
A relationship appearing in a chart is the beginning of an investigation, not the end of one.
Suppose two market series are correlated and one appears to lead the other by several days. That result could reflect a genuine recurring relationship. But it could also be specific to one period, driven by a common third factor, sensitive to the chosen transformation, or too unstable to be useful outside the sample in which it was found.
That is why CauseDecode is designed to look beyond one statistic.
Depending on the data and whether each method is applicable, the analysis can examine partial lead-lag relationships, whether past values add predictive information, out-of-sample behavior, and whether the relationship is stable across periods.
Sometimes these pieces of evidence will point in the same direction. Sometimes they will conflict. Sometimes the correct result will simply be that the available evidence is insufficient.
That is not a failure of the analysis.
An honest “insufficient,” “mixed,” or “not applicable” result can be more useful than a confident answer produced from evidence that does not support one.
CauseDecode Is Designed to Provide a Verification Process, Not a More Plausible Story
Markets do not suffer from a shortage of explanations.
After a move has happened, it is usually possible to find a story that sounds convincing. Rates, inflation, liquidity, positioning, currencies, geopolitics, risk sentiment, and dozens of other factors can all be used to explain the same price movement.
The harder job is deciding which explanations survive contact with the data.
CauseDecode is being built around that distinction. The product is not intended to generate more market narratives. It is intended to make a hypothesis testable: define the two series, prepare the analysis data, examine the relationship across time, and then inspect the evidence rather than jumping directly to a verdict.
The primary output should therefore be the observed facts, numerical results, and charts. Interpretation comes afterward.
That also means the useful outcome is not always finding a strong relationship. Discarding a weak hypothesis is itself a useful research result.
If the data do not support the story, the analyst can stop spending time defending it and move on to a better question.
CauseDecode is currently being developed as a Production MVP. It is not designed to tell users what to buy or sell, and it is not a tool for proving true causality from observational market data.
Its purpose is narrower: to improve the quality of the evidence behind a market hypothesis.
Conclusion: Time-Series Relationships Become Clearer Only After You Prepare and Shift the Data
When two market series move together, it is tempting to draw a straight line from correlation to explanation.
But time-series relationships rarely work that cleanly. Before asking whether one factor “moved” another, we need to define the series correctly, align them, examine what happens when their timing is shifted, and then check whether multiple forms of evidence tell a consistent story.
That is also why correlation is useful but insufficient.
It can tell us that two series moved together. It cannot, by itself, tell us why they moved together, which one came first, whether the relationship is stable, or whether it contains useful predictive information.
CauseDecode is being built to make that verification process easier to perform and easier to inspect.
The goal is not to turn every market narrative into another confident conclusion.
It is to make it easier to ask:
Does this explanation actually hold up when we test it?